
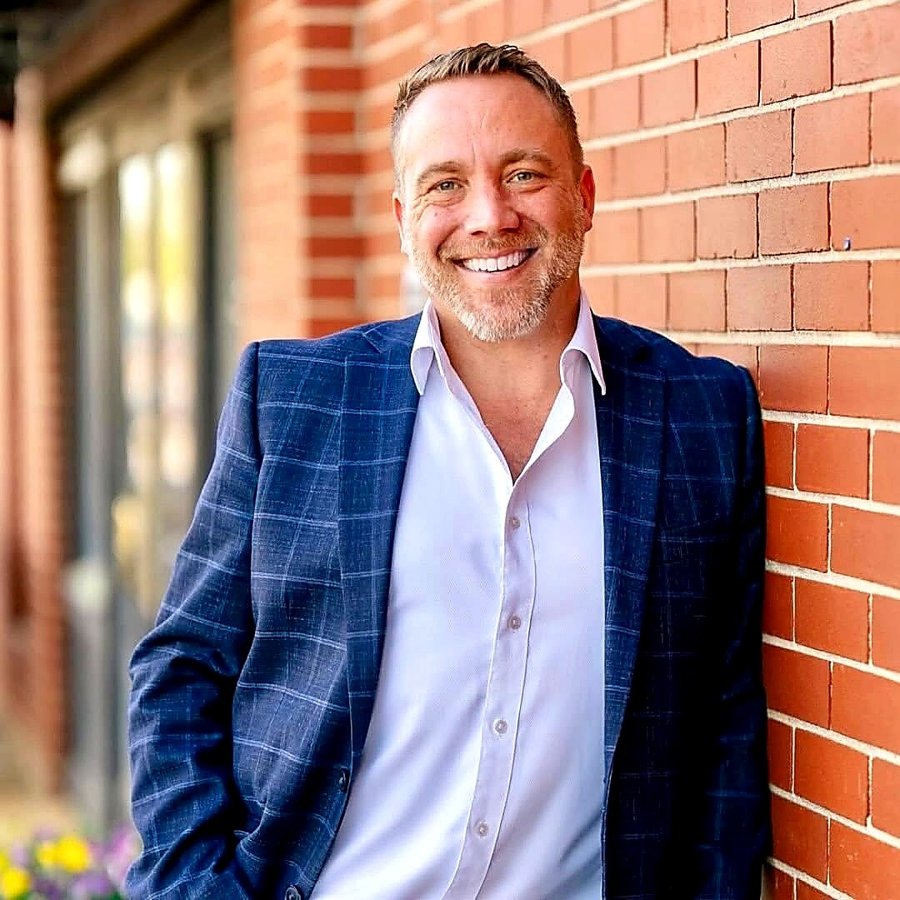
Travis NicolaysenLoan OfficerNMLS #1782820
The biggest loan of your life
deserves a straight answer.
I’m a loan officer in Matthews, North Carolina, working with buyers and agents across Matthews, Concord & the greater Charlotte region, plus upstate South Carolina. Pre-approvals in 24 hours, a phone that gets answered on Saturdays, and an explanation of every number before you sign anything.
Call or text
704-728-4548Same-day reply
tnicolaysen@fairwaymc.comLicensed in
North & South Carolina
 Entity NMLS
#2289
Loan Officer · Fairway Home Mortgage · NMLS #1782820 · Entity NMLS #2289
5.0 · 45 Google reviewsCalls returned
Same day
Seven days a week while a deal is live.
Pre-approval turnaround
24 hours
From a complete application, not a rough guess.
Loan programs
Conv · FHA · VA · USDA
Plus single-close construction, jumbo, renovation and manufactured housing.
Licensed in
NC & SC
Both sides of the state line, one point of contact.
Client rating
5.0 ★
Across 45 Google reviews.
Mortgage solutions
12 programs on the shelf. One of them is yours.
Nobody gets talked into the wrong loan here because it is the only one available. Conventional, FHA, VA, USDA, jumbo, renovation, single-close construction and more — all under one roof.
Not sure which one fits? That is the normal starting point. Six questions on a phone call narrow it down, and the answer is usually not the program you assumed.
Ask me which programWhy work with me
You are not hiring a company. You are hiring me.
I am a mortgage loan officer with Fairway Home Mortgage, working with buyers and real estate agents across Matthews, Concord & the greater Charlotte region, plus upstate South Carolina. Fairway supplies the products, the underwriting and the capacity. What you actually experience is one person who answers the phone and tells you the truth.
What I am good at is the file nobody else wants to underwrite: a business owner whose returns understate what they earn, a manufactured home on five acres, a build on land you already own, a thin credit file that needs sixty days of work before it is ready. Those get solved here rather than declined — and the ordinary purchase gets the same treatment, with the reasoning in writing, the bad news the day it happens, and a closing date that holds.
- You get my mobile number
- A pre-approval that holds up
- You will understand your own loan
- Bad news same day, with options
- The complicated files are the specialty
- "No" is a legitimate answer
Client reviews
Don’t take my word for it. Take theirs.
Unedited, in their words. Communication, availability and getting complicated files closed are the themes that come up most — which is the part of this job that is actually hard.
5.0
45 reviews
#1 Choie for any Mortgage first time buy, refi, and Cash out Refi. Great customer service, responds to every call and text, knowledgeable and experienced, Excellent at communication before performing task to his clients. Answers any questions in a perfessional manner.
Travis and his team are just absolutely wonderful. We just closed on our new house and he was with us every step of the way. This is the 4th time we have used him as our lender over the years and he never disappoints. He is consistent with his knowledge but does it in a way that you feel like you are old friends with him. I tell everyone I know looking to buy a home to call him. I honestly know they will get the same amazing care my husband and I receive by working with him. Can’t say enough good things about him…. If you are looking to buy I highly suggest you reach out to him and his team!
I absolutely recommend Travis for any prospective buyer! As a first time homebuyer, I was really nervous and unsure about the process, but Travis was super helpful every step of the way. He took the extra time to explain everything to me and was always quick to respond to any questions or concerns I had which I really appreciated. Travis made this experience so much less stressful, I felt like I could relax a little since I knew I could count on him. Additionally, he was always a delight to talk to and by the end he was just as excited as me to close on my house, haha. I highly recommend his services especially for any first time homebuyers looking for a supportive and knowledgeable lender!
Travis is the best! He made buying a house on the finance side stress free! My husband and I can’t thank him enough for all he did for us and going above and beyond anytime of the day!
Travis was always there with an answer and guiding me through the whole lending process! Very professional and friendly, feel like I've known him for years...would highly recommend Travis for anyone in the market!!!
Travis is an amazing lender! I always joke I’m going to buy him a cape to wear because he is forever saving a deal!! If you want a lender that’s reliable, PROMPT, knowledgeable and genuinely cares about his customers! I recommend all my buyer clients to Travis!
The company behind me
Personal guidance. National lending strength.
- $25.27B
- Funded in 2025
- 6 years
- USA TODAY Top Workplace
- Nationwide
- Lending footprint
- In-house
- Underwriting & servicing
Loan volume figures are published by Fairway Independent Mortgage Corporation and reflect company-wide originations, not the production of any individual loan officer. Fairway Independent Mortgage Corporation is not affiliated with any government agencies. These materials are not from HUD, VA, USDA or FHA, and were not approved by HUD, VA, USDA or any other government agency.
How the mortgage process works
Six steps, in the order they actually happen.
Most timelines you will read are evenly spaced and wrong. Here is where the time really goes — and where deals stall.
- One conversation
Connect
A call, not an application. What you earn, what you owe, what you have saved, and what you are trying to buy. You leave knowing whether now is the right time and what would move your number.
- 1–2 days
Build your mortgage plan
Documents in one batch, credit pulled, programs compared side by side. You get the payment, the cash to close and the trade-offs for each option in writing — not one quote with no context.
- 24 hours
Get pre-approved
Income and assets verified, file through automated underwriting. A real letter a listing agent can lean on, re-issued at any offer price you need — including on a Saturday.
- As long as it takes
Find your home
Your agent runs this part. I stay reachable for the questions that come up mid-showing: what does this HOA do to my ratio, will this property pass an FHA appraisal, can we close by the 30th.
- 21–30 days
Underwriting & approval
Appraisal, title and underwriting all start at once rather than in sequence. Every condition gets tracked by name until it clears, and you hear about a problem the day it appears.
- About an hour
Closing
Your Closing Disclosure arrives at least three business days early and we read it against your original estimate. Then photo ID, wire confirmation, signatures — and the deed records.
Learn it before you sign it
Everything I’d tell you over coffee, written down.
20 long-form guides, 6 calculators, an FAQ library and a full glossary. No email gate, no download form — just read them.
Estimated monthly payment
$2,410
$308,750 loan · 30 yr · 6.250%
- Principal & interest
- $1,901
- Property taxes
- $230
- Homeowners insurance
- $138
- Mortgage insurance
- $142
Cash down
$16,250
Interest over term
$375,620
Estimate only. Mortgage insurance, taxes and insurance are illustrative and vary by county, credit profile and program. This is not an offer to enter into an agreement or a commitment to lend. Not all applicants will qualify. Information and rates are subject to change without notice. All loans are subject to credit review and approval. Call 704-728-4548 for a quote built on your actual file.
- 02Conventional, FHA, VA or USDA — how to tell which one is yoursLoan programs · 7 min
- 03How much you actually need for a down paymentMoney · 5 min
- 04Closing costs, line by line — and who can pay themMoney · 6 min
- 05What helps and hurts your credit while your loan is in processCredit · 4 min
- 06What a rate lock does — and what it does notMoney · 4 min
Where I lend
Local enough to know which street floods.
Each area guide covers the financing quirk that actually applies there — the condo project review, the septic permit, the jumbo threshold, the county reassessment.
For real estate agents
Your reputation is on the line every time you refer a lender.
I treat that as the actual job. Here is what working together looks like in practice — including a permanent feature page on this site for the agents I partner with.
A 24-hour pre-approval, fully documented
Income and assets verified, file through automated underwriting. Your buyer arrives at the table with an offer a listing agent can trust, not a form letter.
My mobile number, not a call center
Weekends and evenings included while a deal is live. If you need a letter re-issued at a new price during a showing, you get it during the showing.
A straight answer before you write
I will tell you where your buyer’s real ceiling is and what the property has to support for their program — before the offer goes out, not after the appraisal.
Co-branded marketing I actually produce
Listing flyers, open-house financing sheets, payment breakdowns for your listings and social graphics — designed around your brand. I do the work.
Featured agents
Want a page like theirs? Featured agents get a permanent feature here — production record, live listings and all, refreshed as your inventory turns over. Apply to be featured.
Common questions
Asked in nearly every first call.
If yours is not here, ask it directly — you will get an answer from me, not a brochure.
Usually within 24 hours of receiving a complete document set — pay stubs, W-2s or returns, and asset statements. The bottleneck is almost never underwriting; it is documents arriving one at a time.
No, and you never did. Conventional loans start at 3% down for qualifying first-time buyers, FHA at 3.5%, and both VA and USDA can be zero down for eligible buyers and properties. Twenty percent removes mortgage insurance — it is not a requirement to qualify.
Conventional programs generally start around 620, FHA around 580, and VA has no set floor. Score is only one input, though — debt-to-income ratio and documented reserves often matter more. If your score needs work, I will tell you exactly which balances to move and roughly what it should do.
Multiple mortgage inquiries inside a 45-day window are treated as a single event by the credit scoring models. Shopping is explicitly protected. Get Loan Estimates from more than one lender and compare them line for line.
A pre-approval costs nothing. The first real out-of-pocket expense is the appraisal once you are under contract, typically $550–$800 in this market.
Yes — South Carolina as well, which matters constantly given how many Charlotte buyers end up in Fort Mill, Indian Land or Rock Hill.
Yes, and it is a real specialty. Permanent foundations, retired titles, private well and septic, and outbuildings on multi-acre parcels are routine west of Charlotte. There is a full guide on this in Mortgage 101.
We do it here. Our single-close construction loan covers the land, the build and the permanent mortgage in one closing before ground breaks — interest-only while the house goes up, then it converts to permanent financing automatically at the Certificate of Occupancy. Site-built, modular and eligible manufactured homes all qualify. Builders can get approved with us too.
It is a documentation question, not a barrier. Standard programs average two years of net profit with add-backs; bank-statement programs qualify you on deposits instead of tax returns when write-offs make the returns unrepresentative.
Pre-approval is based on a preliminary review of credit information provided to Fairway Independent Mortgage Corporation and has not been reviewed by underwriting. Final loan approval is subject to a full underwriting review of supporting documentation, including but not limited to applicant’s creditworthiness, assets and income information, and a satisfactory appraisal.
Next step
Buying, selling, or referring — let’s start the conversation.
No form disappearing into a queue. You will hear back from me, usually the same day, with the specific next step for your situation.